The recent High Court decision in Elliott v The Members of Lloyd's Syndicate 4444 [2026] EWHC 1773 (TCC) provides valuable guidance for insurers dealing with subsidence claims and allegations of fraud. While the insurer was ultimately successful, the judgment reinforces that fraud remains a serious allegation requiring strong evidence, while also demonstrating the value of thorough investigations into a property’s claims and damage history.
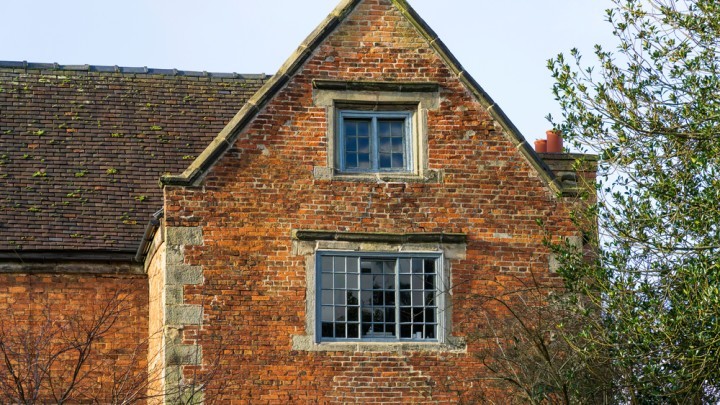
Mr Elliott pursued a subsidence claim under a household policy relating to “The Old Vicarage”, a Grade II listed property in Bedfordshire. He alleged that subsidence damage had occurred during the policy period and sought substantial damages from insurers.
However, investigations revealed a lengthy history of subsidence concerns at the property, including:
The insurer also alleged fraud after discovering that a quotation submitted in support of the claim had been altered to give the impression that proposed building works related to structural underpinning and subsidence repairs when, in reality, they concerned the conversion of garage space.
The Court dismissed the claim in its entirety. It found that Mr Elliott had failed to establish that insured subsidence damage occurred during the policy period and concluded that the evidence instead demonstrated longstanding and pre-existing issues.
Importantly, the Court also found that Mr Elliott had knowingly relied upon a false quotation in support of his claim. Applying the principles in Versloot, the Court held that this was not merely a collateral issue but formed part of a fraudulently exaggerated claim. As a result, the entire claim was forfeited.
1. The evidential bar for fraud remains high
Fraud continues to be one of the most serious allegations an insurer can make. As highlighted in recent fraud litigation and industry guidance, courts require clear and compelling evidence before making such findings. Mere suspicion, inconsistencies or concerns about credibility will rarely be sufficient in isolation.
In Elliott, the insurer succeeded because it was able to produce persuasive documentary evidence demonstrating that a quotation had been deliberately altered and submitted in support of the claim. The fraud finding was driven by evidence, not inference.
2. Pre-inception damage remains a critical issue
Perhaps the most practical lesson from the case is the importance of thoroughly investigating a property's history.
The insurer’s success was underpinned by evidence showing that cracking, movement and subsidence concerns pre-dated policy inception. Historic claims files, expert reports, previous litigation and contemporaneous correspondence all played a central role in undermining the allegation that insured damage had occurred during the policy period.
For subsidence and property claims in particular, insurers should ensure investigations consider:
3. Fraud is not always the only answer
The judgment also serves as a reminder that insurers should consider all available coverage and causation defences before reaching for fraud allegations.
As recent case law has demonstrated, proving fraud is difficult and can expose insurers to significant litigation risk if the evidence is not sufficiently robust. In many cases, a straightforward coverage defence, policy exclusion, causation argument or evidence of pre-existing damage may provide a stronger and more proportionate route to claim denial.
Elliott is not a decision that lowers the threshold for proving fraud. If anything, it reinforces the principle that fraud findings will only follow where there is cogent evidence of dishonesty. However, it is an encouraging outcome for insurers where investigations uncover compelling documentary evidence.
More broadly, the case demonstrates the value of digging into the history of a claim and a risk. In property claims, particularly subsidence matters, establishing what happened before policy inception can often be every bit as important as investigating the loss itself.
Jessica Taylor - Senior Associate
Jessica Taylor
Designed to elevate the policyholder experience and empower handlers, ClaimPilot transforms the claims journey with state-of-the-art AI, streamlined processes and reduced operational bottlenecks – all in one powerful platform.